-
Bank credit to Nigeria’s manufacturing sector fell sharply even as banks raised ₦4.65 trillion under the recapitalisation programme. Reports said the decline highlights growing concern that fresh banking capital is not yet reaching productive sectors such as industry and small businesses.
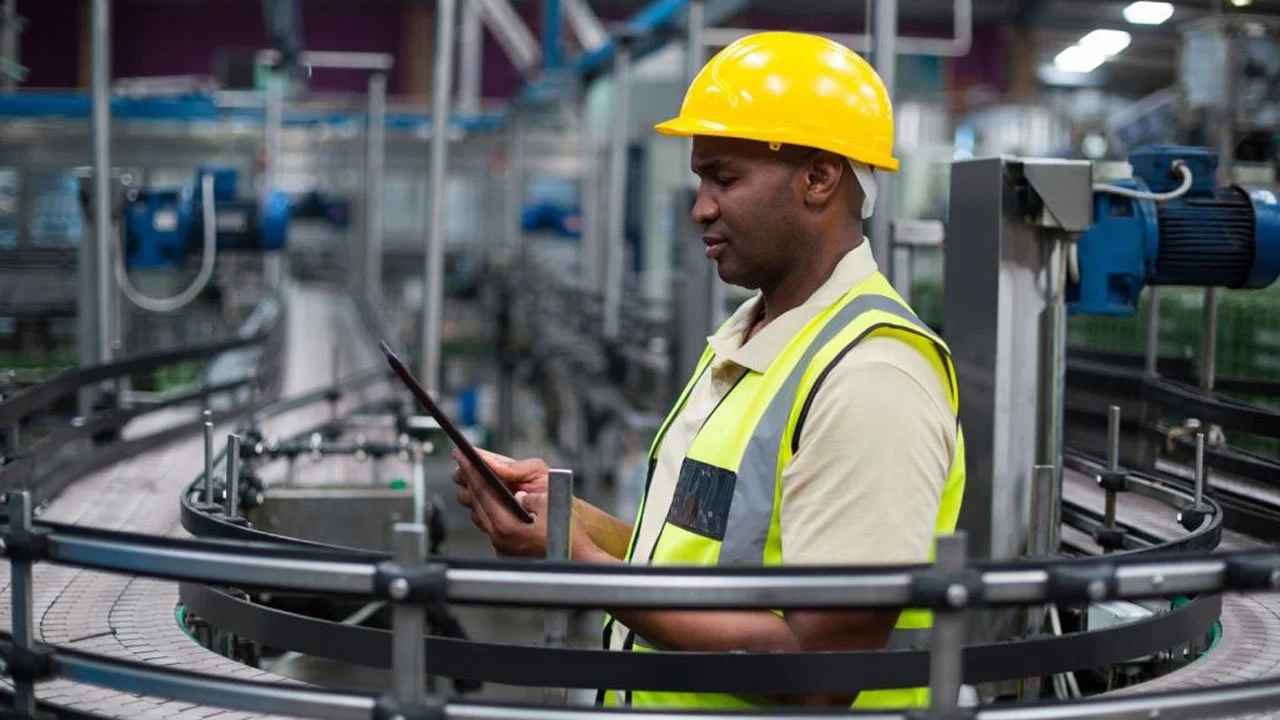
Bank credit to Nigeria’s manufacturing sector dropped 33.8 per cent between December 2024 and August 2026, according to figures presented at a banking event in Lagos.
BusinessDay reported that manufacturing credit fell from ₦8.53 trillion in December 2024 to ₦5.65 trillion in August 2026. The figures were presented by the Chief Executive Officer of the Nigerian Economic Summit Group, Tayo Aduloju, at the Chartered Institute of Bankers of Nigeria 2026 Fellowship Investiture.
The reports also said Nigerian banks raised ₦4.65 trillion in fresh capital under the ongoing recapitalisation programme. A total of 33 banks were said to have met the new minimum capital requirements.
Despite that capital raise, manufacturing’s share of total bank credit fell to 8.7 per cent. Speakers at the event urged banks to direct more of the new capital into productive sectors, including manufacturing, small and medium-sized enterprises, and broader industrial growth.
The development points to a gap between stronger bank balance sheets and the flow of lending to businesses that make goods, create jobs and support domestic production. The reports did not say why manufacturing credit fell during the period, but the figures presented at the event added to concerns about credit access for the real economy.
Why It Matters
Manufacturing is a key part of economic activity because it supports jobs, supply chains and local production. A sustained drop in bank lending to the sector can limit expansion by factories and weaken efforts to grow output at home.
The figures matter beyond the banking industry because recapitalisation is often expected to improve banks’ ability to support business growth. If more capital does not translate into stronger lending to productive sectors, the wider economic benefit may be limited.
What It Means for Your Money
For households and business owners, this report may matter if weaker access to credit continues to affect manufacturers and smaller firms. That can put pressure on production, business expansion and jobs, but the reports did not provide any direct consumer price or income effect.
There is no immediate personal-finance action in the report, and no investment advice follows from it on its own.
-
What merits close monitoring is whether banks begin to increase lending to manufacturing, SMEs and other productive sectors after the recapitalisation push. Future banking data and public comments from lenders, regulators and industry groups will help show whether the fresh capital is being converted into broader business credit.
Readers should also watch whether manufacturing’s share of total bank credit improves from the reported 8.7 per cent
Closing Summary
The key takeaway is that Nigerian banks have raised significant new capital, but lending to manufacturing has still fallen sharply. That contrast is now raising pressure for more of the banking sector’s stronger capital base to reach the productive economy.
Five stories, the key numbers, and why they matter. Free, no ads.
Subscribe free