Many Nigerians notice small bank alert deductions but ignore them because each one looks minor. Over a month, however, alert costs across multiple accounts can quietly add up. The smarter move is not to switch everything off blindly. It is to decide which alerts you truly need, which account should carry them and how to keep enough visibility to catch fraud, failed reversals and unexpected charges quickly.
Know what you are paying for
In Nigeria, SMS transaction alerts are generally charged on a cost-recovery basis for customer-induced transactions, while email notifications are typically free. That means your bank may recover the telecom cost of sending SMS alerts, but email should not attract the same type of charge.
This matters because many people keep SMS alerts active on every account they own: salary account, savings account, side-hustle account and sometimes an old account they barely use. If money moves often, repeated SMS charges can become a regular expense you did not consciously choose.
Do not turn off alerts without a plan
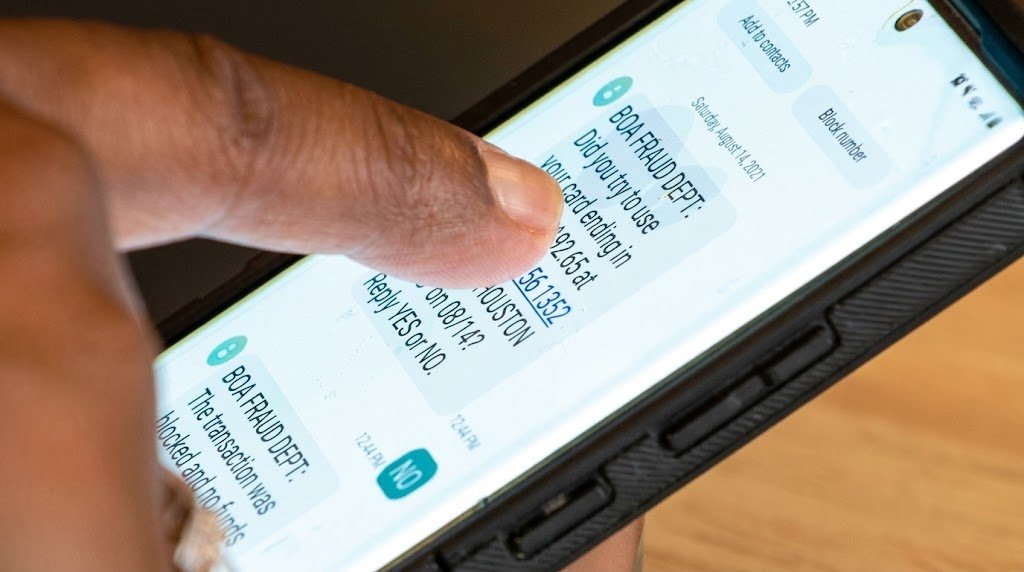
Alerts are not just convenience. They are part of your early-warning system. A debit alert can help you spot an unauthorised transfer, a card payment you did not make or a charge that should be challenged. If you disable alerts completely and stop checking your account, you may discover a problem too late.
A better approach is selective control. Keep the fastest and most visible alerts on the account you use most for spending. If you maintain more than one account, consider whether every account really needs SMS alerts, especially those you use only for storing money and rarely touch.
Use one main transaction account
One practical way to cut alert costs is to simplify your banking structure. Use one account for everyday inflows and outflows, and keep your other accounts quiet. If salary enters one account but you spend from another, you may be paying for alerts in both places every time you move money around.
This does not mean everyone needs only one bank account. It means each account should have a job. Your spending account handles regular transactions. Your savings account should have fewer movements. Fewer transactions usually mean fewer chances for repeated alert charges.
Choose email well, not carelessly
Switching to email alerts can reduce costs, but only if you actually read them. Use an email address you check often and set a rule or folder so bank messages do not get buried. If your bank app allows push notifications, use them too, but do not rely on an app you rarely open.
Before changing alert settings, confirm the process with your bank and keep a record of the request. If you later notice charges that do not match the arrangement on your account, raise it promptly through the bank’s complaint channels and escalate if the issue is not resolved.
The goal is not to remove every alert. It is to stop paying for account activity you do not need while keeping enough visibility to protect your money. If you review your accounts, reduce unnecessary transfers and use email or app notifications wisely, you can trim a recurring cost without weakening your control over your finances
Five stories, the key numbers, and why they matter. Free, no ads.
Subscribe free