One reason salaries disappear too quickly is that every expense is fighting from the same pot. Transport, airtime, food delivery, transfers to friends and fixed bills all sit in one account, so it becomes hard to tell what is safe to spend. A separate bills account will not increase your income, but it can give your money structure. That structure can reduce accidental overspending, missed payments and the stress of discovering too late that rent, school fees or utility money has already been eaten up by everyday spending.
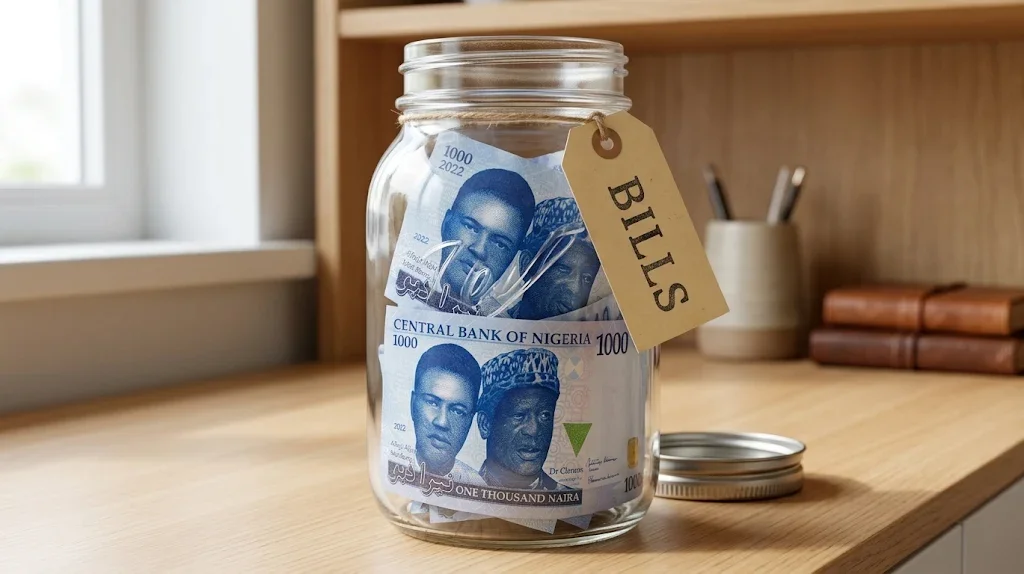
Give important money a different job
A bills account is simply an account you use for planned obligations, not for casual spending. Once your salary lands, you move the amount meant for rent, electricity, internet, loan repayment, school runs or family support into that account and leave it there for those purposes.
This works because money behaves differently when it has a clear assignment. If your debit card, transfer app and daily spending all point to one account, small transactions can quietly consume money you had mentally reserved for something important. Separation adds friction, and that friction is often useful.
Keep your main spending account lean
Your regular account can then become your day-to-day spending account. That is the one for transport, lunch, airtime, data and the small requests that tend to show up during the month. When that balance starts running low, you get an earlier warning that your flexible money is almost finished, without touching what you already set aside for essentials.
This approach also makes your statement easier to read. When bills are grouped in one place, it is quicker to confirm whether a payment went through, whether a direct debit happened twice or whether a charge looks wrong. Cleaner records help you act faster when there is an error.
Set it up in a way you can maintain
Keep the system simple. Choose one account for income and everyday spending, and one for fixed commitments. On payday or within 24 hours, move money for non-negotiable expenses first. If your income is irregular, transfer smaller amounts into the bills account each time money comes in instead of waiting for a perfect lump sum.
It is also wise to leave a small cushion in the bills account for timing issues. A transfer delay, a slightly higher utility payment or a bank charge should not be enough to cause a failed payment if the account is carrying a modest buffer.
Watch the charges and review every few months
Before using any account as your bills account, check the charges attached to it and how alerts, transfers and card use may affect the balance. A bills account works best when it is quiet. If possible, do not tie it to unnecessary subscriptions, impulse purchases or multiple cards.
Review the system every few months. Rent may rise, school costs may change and a loan may end. The goal is not to create a perfect arrangement once and forget it. The goal is to give essential money protection before the rest of the month begins.
A separate bills account is not about having more money. It is about protecting the money that already has a job. If you move essentials out of your everyday spending stream as soon as income arrives, your salary becomes easier to manage, your records become clearer and costly surprises become less frequent.
Five stories, the key numbers, and why they matter. Free, no ads.
Subscribe free